Gold Under Pressure as Bond Yields and Dollar Stay Elevated, Speculators Cut Longs
GOLD PRICES remained under pressure on Monday despite a sharp drop in expectations for a Fed rate hike in October, as Treasury yields stayed near multi-decade highs and a weaker Euro supported the Dollar. The latest CFTC data meantime showed money managers cutting their net bullish positioning in Comex gold futures and options for a fifth consecutive week, writes Atsuko Whitehouse at BullionVault.
Spot gold fell 0.9% to $4153 per ounce by Monday lunchtime from Friday’s London afternoon benchmarking auction price after recording its sixth consecutive weekly decline. Last week, gold touched its lowest level since 5 August, erasing August’s gains. On Friday, gold gave up its initial gains following weaker-than-expected US jobs data.
The odds of an October rate hike have fallen to just above 20%, down from over 70% a week earlier, although the probability of at least one hike by December remains above 80%, according to CME’s FedWatch tool. Yet US 10-year Treasury yields held near their highest since 2002.
French fiscal concerns kept the spread between French and German 10-year yields around 145 basis points, close to Friday’s widest level since the Eurozone debt crisis in 2011. The Euro fell to a 17-month low against the Dollar, helping lift the Dollar index to its highest since April 2025. Spain’s Prime Minister Pedro Sánchez this morning called a snap election for 29 November, adding to political uncertainty in the Eurozone.
“Gold’s price action looks a little worrying,” said Jeff Toshima, former Tokyo director of the mining industry’s World Gold Council and a regular columnist for Nikkei, noting that gold plunged nearly $100 from the level it reached immediately after the release of weaker-than-expected US jobs data, despite receding expectations of a Fed rate hike.
“I expect strong buying interest from central banks and long-term investors on dips toward $4000,” he added.
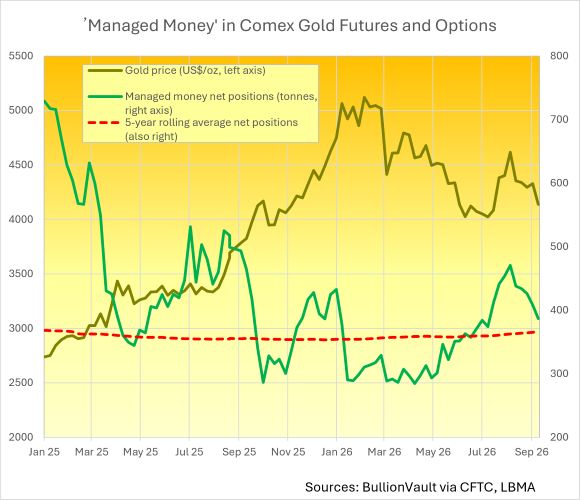
While Toshima expects buying interest from longer-term investors, speculative Managed Money net longs in Comex gold futures and options fell for a fifth consecutive week to 386.98 tonnes as of Tuesday, 29 September. Despite the decline, net bullish positioning remained 5.6% above its trailing five-year average of 366.48 tonnes.
The latest positioning contrasts with earlier stages of this year’s rally. On 24 February, gold reached $5120 per ounce, the highest LBMA PM price on record for a Tuesday, yet Managed Money net longs stood at 310.84 tonnes, 12.3% below their trailing five-year average.
By 25 August, net longs had climbed to 470.64 tonnes, 29.8% above their five-year average, while gold’s PM price stood at a lower $4615. Over the following five weeks, net longs fell 17.8%, while the Tuesday PM gold price dropped 10.3% to $4139.
“Gold continues to highlight a notable divergence: hedge funds cut 2.7 million ounces of exposure during September, while ETF investors added 1.7 million ounces, lifting holdings to a four-year high,” said derivatives platform Saxo Bank's commodity strategist Ole Hansen.
That divergence continued last week, with holdings in SPDR Gold Shares (GLD) and iShares Gold Trust (IAU), the world’s two largest gold-backed ETFs, both increasing. GLD added 1.1 tonnes (0.11%) over the week, despite a 0.86-tonne outflow on Friday. IAU added 0.6 tonnes (0.13%), including 0.3 tonnes on Friday, taking its holdings to 463.54 tonnes, the highest since 23 September.
Brent crude futures edged up 0.3% to $102.58 per barrel on Monday, as concerns over continued Middle East supply disruptions offset rising crude exports from the region and plans for a G7 release of emergency oil stocks.
Key OPEC+ members agreed over the weekend to keep November production targets unchanged. Kpler shipping data showed crude exports from the Middle East Gulf region, excluding Iran, returned to pre-war levels in September, although shipping routes remained disrupted.
Silver, which derives nearly 60% of its annual demand from industrial uses, rose 1.1% to $61.68 per ounce by lunchtime in London, compared with Friday’s London silver benchmarking auction price. The grey metal fell 6.1% last week, marking its second consecutive weekly decline.
Gold priced in Euros meantime edged lower by 0.3% to €3704 per ounce, while the UK gold price fell 0.7% to £3139 per ounce from Friday’s London afternoon benchmarking auction price.
Over the weekend, France’s education minister announced that up to 500 high schools would remain fully or partly closed on Monday following nationwide student protests. Further demonstrations are planned for Tuesday, with the CGT, one of France’s main trade union federations, urging workers to join, adding to pressure on a government already struggling to secure support for its 2027 budget.
“We continue to view rising government debt levels as a structural tailwind for the yellow metal,” said UBS analyst Giovanni Staunovo, noting that gold was holding up relatively well despite higher interest rates and a stronger US Dollar.




 Email us